13 August 2026
Inflation cools, markets stay quiet — Nasdaq ticks higher, gold sits in a range
The week of August 10–14 was relatively calm after last Friday’s NFP shock. No panic, no capitulation, no new breakout — just two inflation prints that came in as expected, or slightly cooler, and a slow drift higher in equities. As Bloomberg’s wrap put it, Asian stocks were set for gains as US inflation cooled, while gold paused after a run to a two-month high.
July CPI rose 0.1% month-on-month and 3.4% year-on-year, both in line with forecasts. Core CPI eased to 2.5% annually — the slowest pace since March 2021. Thursday’s PPI was quieter still: headline wholesale prices unchanged at 0.0% versus +0.2% expected. September hike odds slipped below 50%, toward roughly 40%. The Nasdaq ticked higher — +0.54% on Wednesday to 26,588, then another ~0.8% on Thursday as the S&P 500 notched a record. Gold, after last week’s discovery push, stopped extending and started trading a range.
CPI and PPI: no surprise, and that was the point
The inflation week did not shock anyone, which is why the tape stayed orderly. Gasoline fell 2.9% on the month and helped the headline; core services remain the sticky piece. Wells Fargo’s Gary Schlossberg said the CPI reading plus last week’s weak jobs report “may keep hawkish Fed officials at bay in September” — though oil tied to the Middle East still leaves the outlook guarded.
PPI at 0.0% followed June’s decline, so the producer pipeline is not re-accelerating. Markets treated both prints as permission to wait: another CPI and another jobs report still land before the September 15–16 FOMC. Warsh has given no forward guidance, so Jackson Hole at the end of August is the next place he might “frame the big questions” without telegraphing a hike.
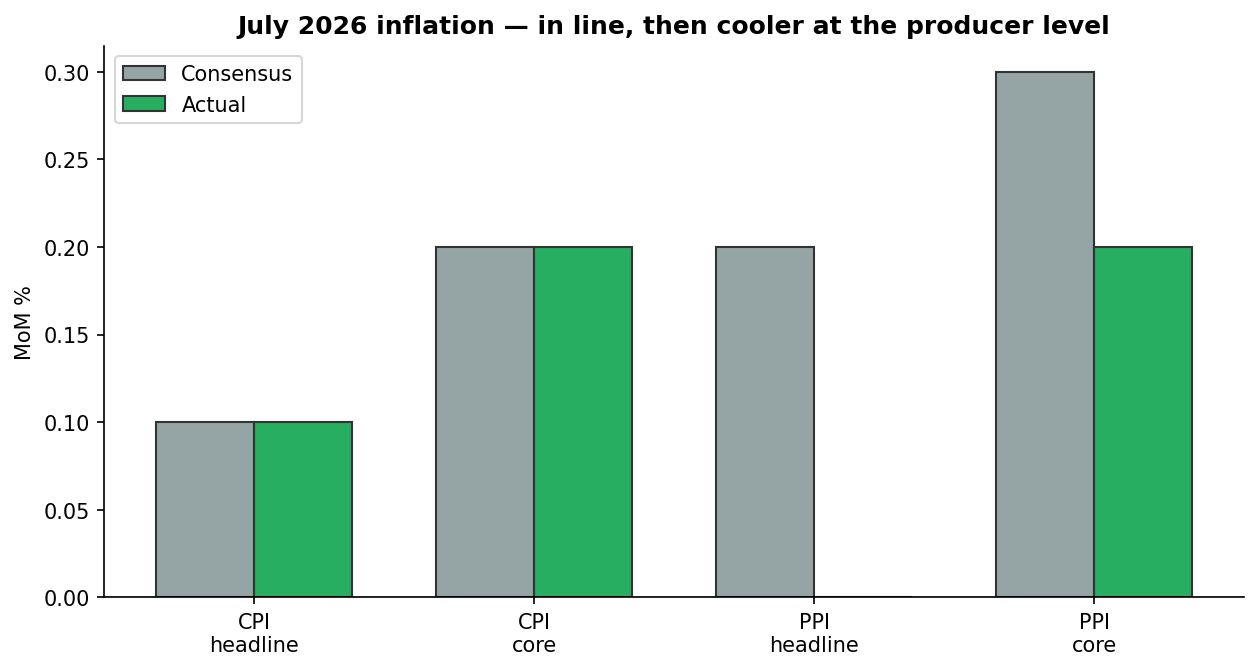
July 2026 CPI and PPI. Source: BLS / Bloomberg
Probabilities of different interest rate scenarios for September 2026. Source: https://www.cmegroup.com/markets/interest-rates/cme-fedwatch-tool.html
Equities: a quiet US uptick, a louder rebound in Asia
The US stock market showed an uptick, not a melt-up. The Nasdaq led as AI-linked names recovered some of July’s de-rating. The S&P 500 pushed to a fresh record on Thursday. The Dow lagged — this is still a rate-and-tech tape.
Asia was the louder version of the same story. South Korea’s Kospi jumped around 3.7–4.4% into a technical bull market, with Samsung and SK Hynix leading. Bloomberg described a return of “long Korea, short Hong Kong” after July’s unwind. Pictet’s Arun Sai called it the early innings of the capex cycle after markets had “digested the historical unwind in the momentum trade.” Earnings still split the tape: CoreWeave helped, Cisco and Cerebras sold off.
Brent snapped a six-day rally and slipped back under $88. The quiet constraint underneath the calm is the long end of the Treasury market: a 10-year auction printed the highest yield since 2007, and a 30-year sale was set at the highest financing rate in 25 years.
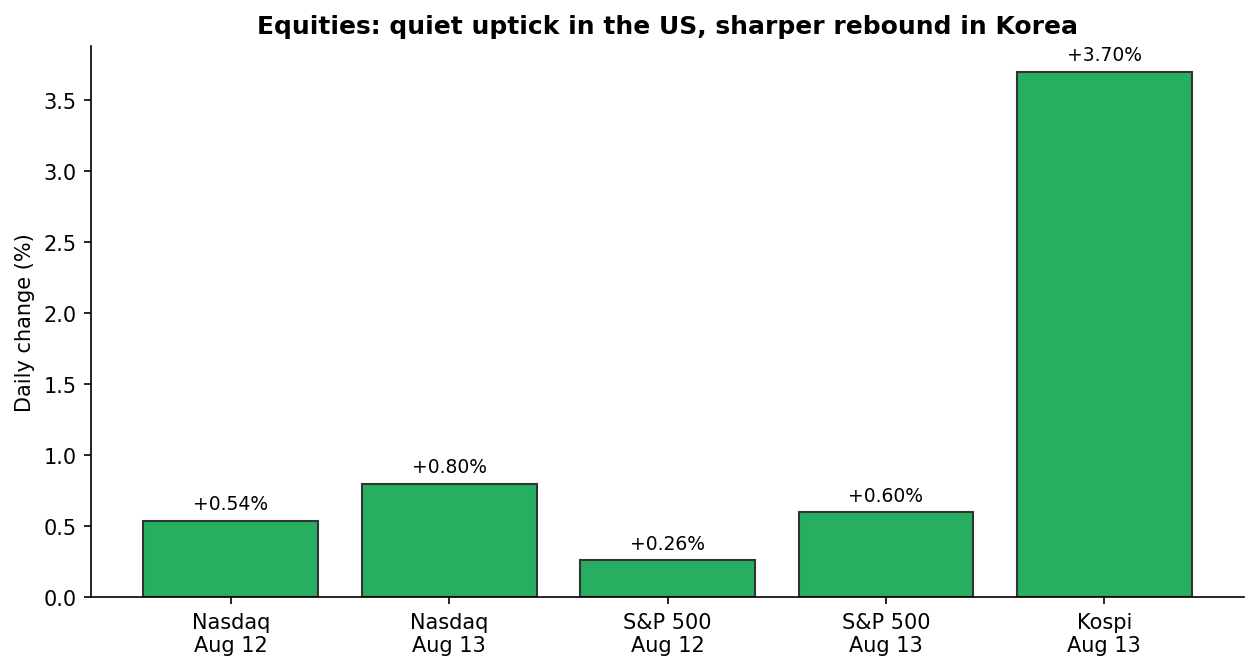
US and Korea equity moves around the CPI week. Source: Bloomberg
News in focus
Friday, August 14: July retail sales; University of Michigan inflation expectations.
August 26: Nvidia earnings — the next real test of the AI rebound.
August 27–29: Jackson Hole — Warsh’s first symposium speech as chair.
September 15–16: FOMC. September hike odds now around 40%.
Now let’s shift to potential scenarios and trading ideas for the week ahead.
Gold
XAUUSD is no longer in a clean discovery extension. After the NFP breakout and a spike toward $4,430–4,450 on the CPI day, gold paused and is sitting in a sideways range roughly between $4,350 and $4,450. PPI barely moved the metal. That is typical after a fast swing: the market needs time to absorb the new level.
The constructive case is that the range is a pause, not a reversal — a hold above $4,350 keeps the bullish structure intact into Jackson Hole. A break above $4,450 would reopen swing expansion toward $4,500. The risk is a dollar bounce or a hawkish Warsh tone that drops gold back toward $4,280–4,320, last week’s breakout zone.
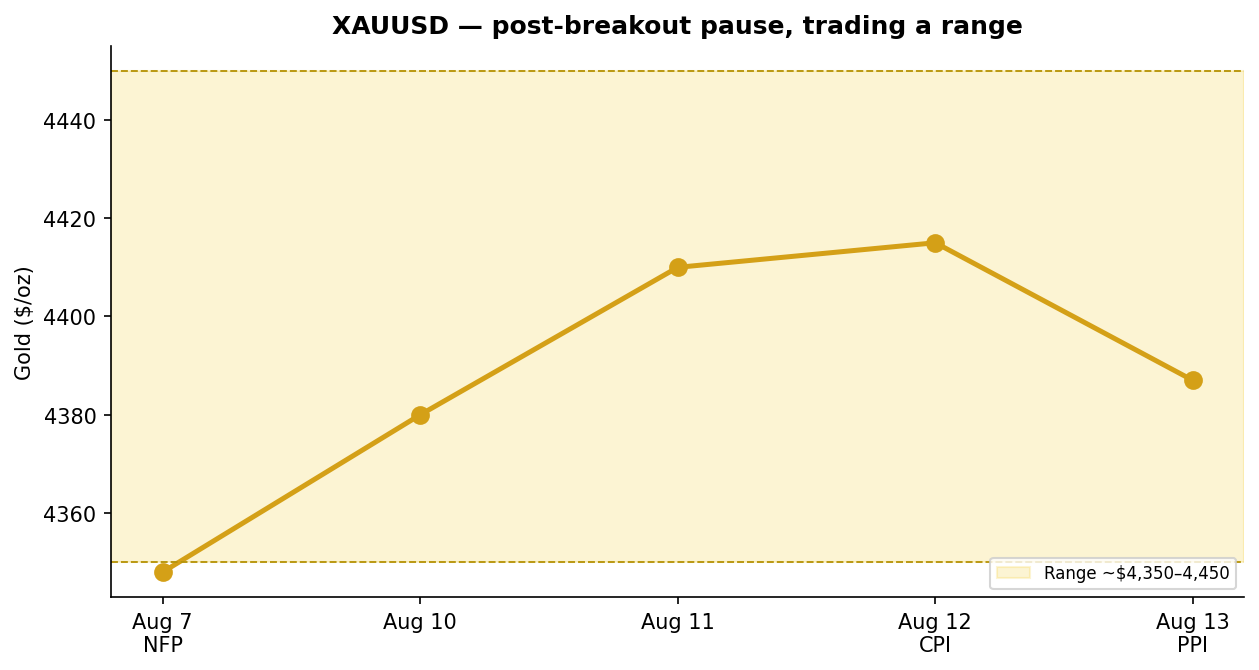
XAUUSD, daily chart. Source: Exness.com
Nasdaq
The Nasdaq used the cool CPI/PPI week to tick higher and reclaim the area it was testing as resistance last week. The uptick is real, but it is still a quiet grind. As long as the index holds 26,400–26,500, the path of least resistance stays mildly higher toward 27,000.
If that support fails, a slide toward 25,800–26,000 remains on the table — especially if Nvidia disappoints or Warsh sounds less willing to wait. For now, the market is treating softer inflation as enough to buy dips, not enough to chase.
USTEC, daily chart. Source: Exness.com