6 August 2026
Gold enters price discovery after NFP shock — CPI week ahead
The week of August 4–8 started with record highs on the Dow and S&P 500, driven by earnings optimism and hopes for a US–Iran deal. By Thursday, Iranian state media published a restrictive Hormuz draft plan, Brent rebounded nearly 4% to $82.48, and yields climbed — the Dow fell 0.85%, the S&P slipped 0.18%. As Bloomberg noted, markets paused ahead of Friday's jobs report.
Friday flipped the tape. Nonfarm payrolls fell by 23,000 in July versus a +80,000 forecast, with May/June revisions removing 103,000 jobs. Unemployment dipped to 4.1% only because participation fell to 61.4%. September hike odds dropped from ~58% to ~42%, yields fell, and gold surged to ~$4,348. The S&P closed at a record 7,757.64 (+0.62%); the Nasdaq rose 1.30% to 26,690.62. Bad news for the economy became good news for rate-sensitive assets — but the move stays fragile until Wednesday's CPI.
Thursday–Friday: oil, NFP, and the reversal
Thursday's pullback was geopolitical. Bessent's Hormuz deal hopes faded as Fars published a plan banning US and Israeli vessels, with penalties up to 20% of cargo value. Earnings added pressure — Western Digital (-13%), Datadog (-19%), Honeywell Aerospace (-23%) — as beats paired with soft guidance triggered selloffs in stretched names.
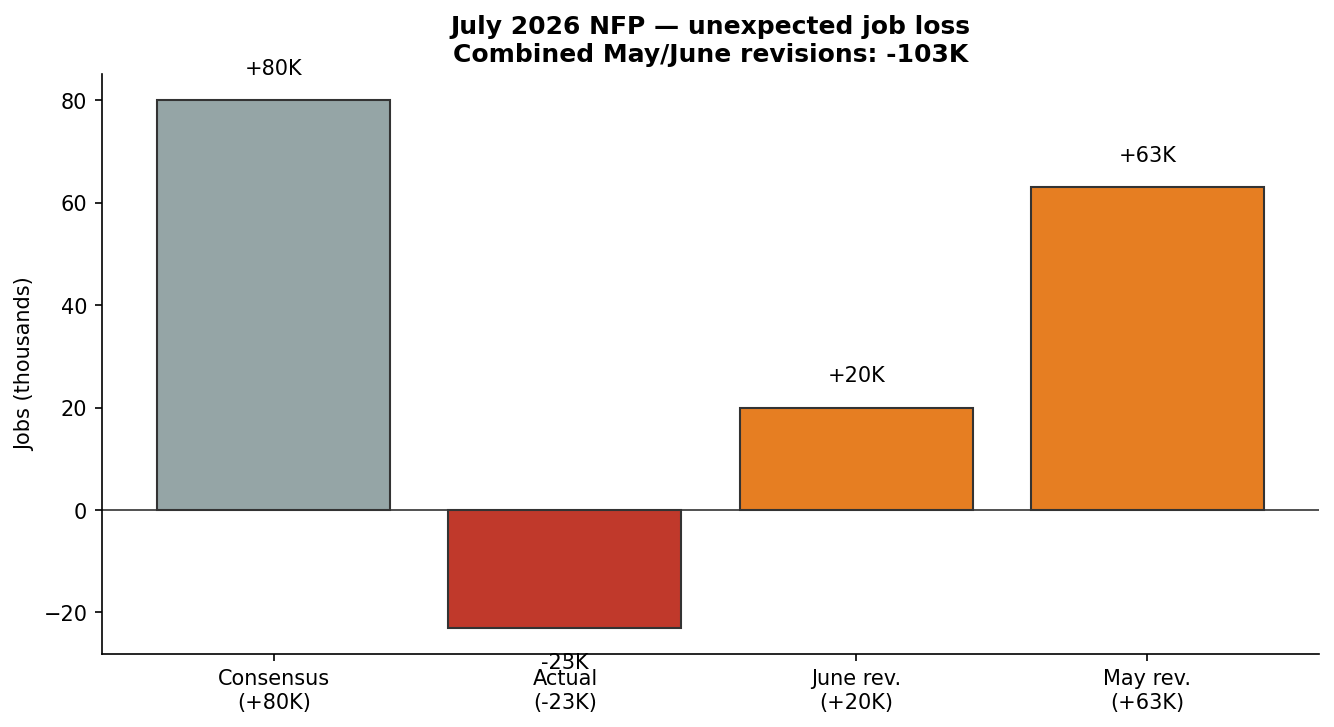
July 2026 NFP — unexpected job loss. Combined May/June revisions: -103K. Source: https://tradingeconomics.com/united-states/non-farm-payrolls
Friday's weak print drove a classic "bad news is good news" reaction: gold +2.4% (best week in seven months), 10Y yield -6bp to 4.61%, dollar to a seven-week low. SpaceX +12% despite lockup expiry; memory stocks lagged.
CPI week: the binary test
The July CPI on Wednesday, August 12 (8:30 ET) is the week's key release. Warsh's July FOMC came before this data — Wednesday's print either confirms disinflation and extends Friday's rally, or revives the September hike trade. Consensus: headline +0.1% m/m, core +0.2% m/m. A hot print threatens gold's breakout and Friday's equity gains; a soft one keeps hike odds below 45%.
Probabilities of different interest rate scenarios for September 2026. Source: https://www.cmegroup.com/markets/interest-rates/cme-fedwatch-tool.html
News in focus — the week of August 10
Wednesday, August 12: July CPI — high impact.
Thursday, August 13: July PPI.
Friday, August 14: July retail sales.
Ongoing: Hormuz talks; Brent near $82.
Now let's shift to potential scenarios and trading ideas for the week ahead.
Gold
XAUUSD has entered price discovery mode — the primary idea for the week. The metal broke above its seven-week high near $4,271 and closed near $4,348, with no immediate overhead reference. Falling yields, a weaker dollar, and Hormuz safe-haven demand support a bullish swing expansion toward $4,400–4,450 ahead of CPI, holding $4,280–4,320 as support.
The main risk is a hot CPI print — that would revive hike odds, lift yields, and pull gold toward $4,150–4,200, ending the discovery phase.
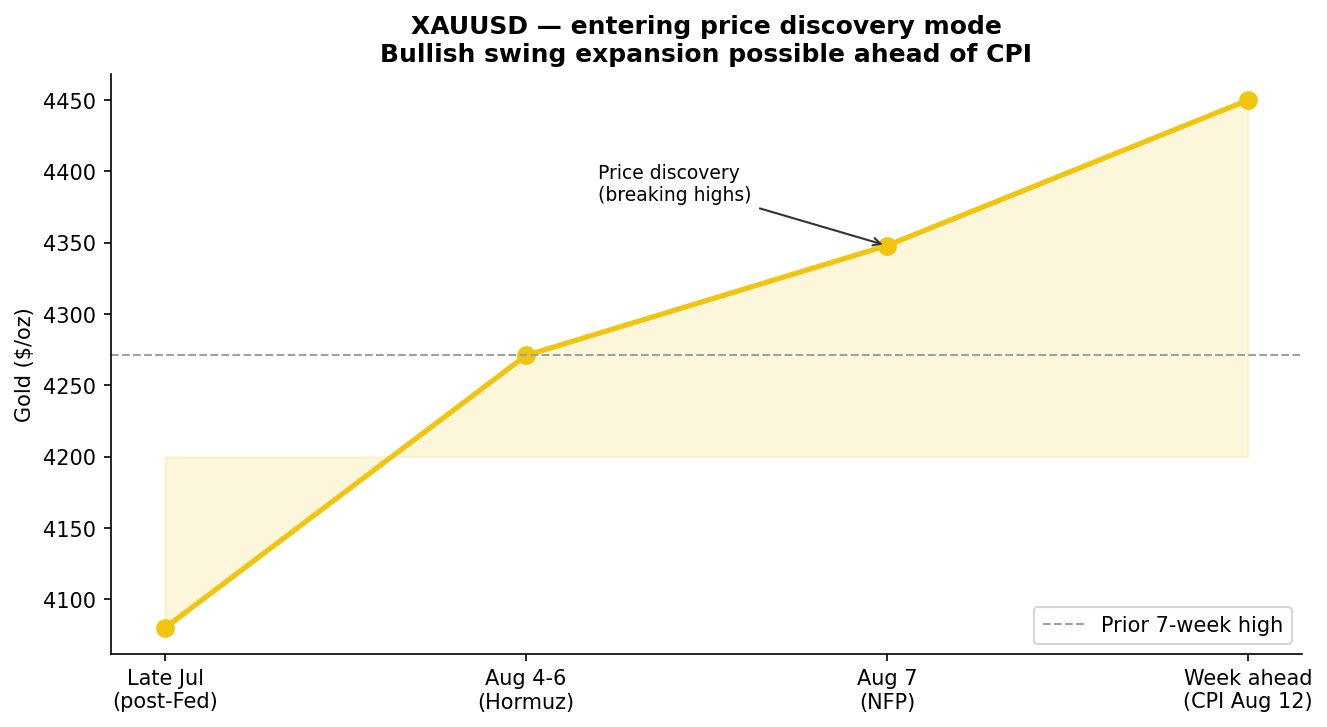
XAUUSD, daily chart. Source: Exness.com
Nasdaq
The Nasdaq at 26,690 sits in a resistance zone at 26,600–26,800, where Friday's rate-driven rally meets overhead supply from July's AI de-rating. The index needs bullish support near 26,400–26,500 to target 27,000+ on a soft CPI. Without it, the likely path is a slide toward 25,800–26,000 — especially if CPI surprises hot.
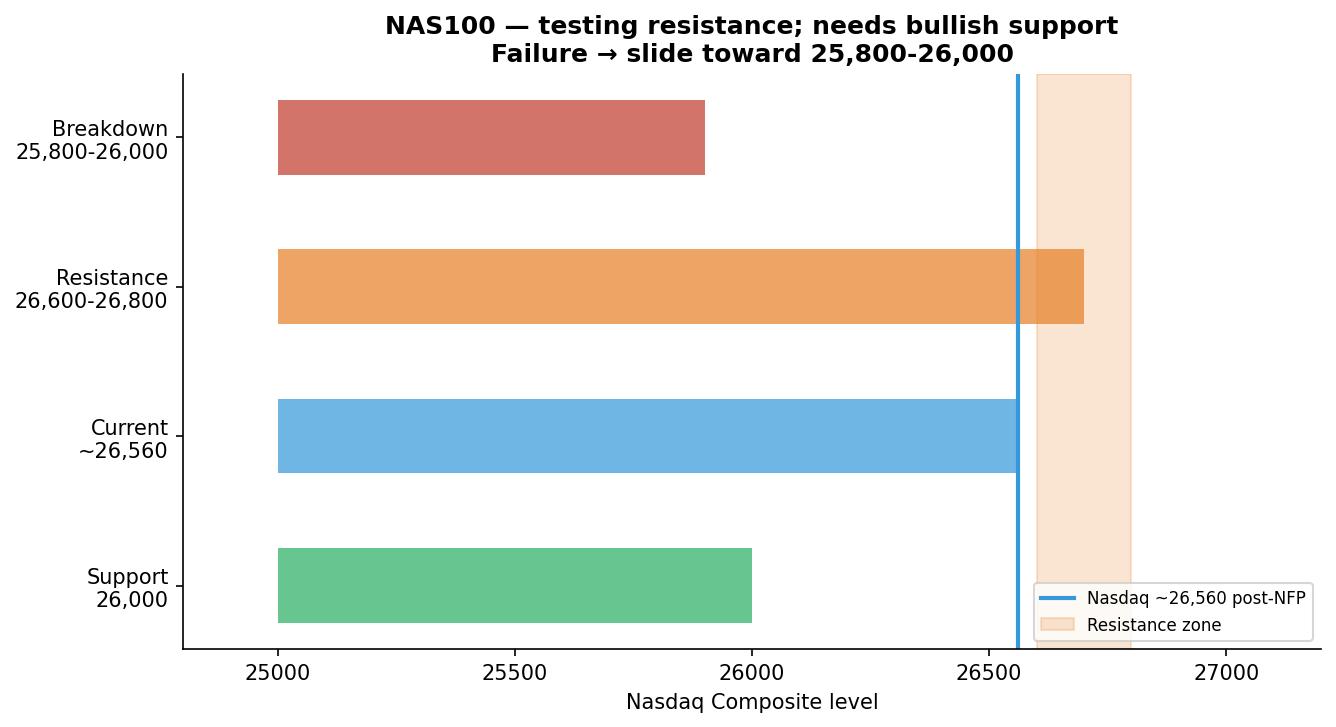
USTEC, daily chart. Source: Exness.com