30 August 2026
Warsh talks hike, bonds stay wary — stocks drift, gold gives it back
The week ended with Kevin Warsh’s first Jackson Hole speech as Fed chair — and with a split that Bloomberg’s Sunday wrap captured cleanly. Stocks drifted lower. The bond market prepared for a rate hike. And a second Bloomberg piece said what the long end is actually thinking: investors are wary. Swaps priced a September move as more likely than not, but asset managers still doubt Warsh will follow through.
The numbers on Friday were modest. The S&P 500 fell 0.2–0.3% to about 7,712. The Nasdaq slipped 0.5% to 26,402. The Dow barely moved. That was not a crash. It was a market that had already spent the week on Nvidia’s beat and a firm PCE print, then heard Warsh say inflation remains the job. September hike odds jumped from roughly 35–36% before the speech to about 57–58% after it. Two-year yields rose almost 12 basis points to 4.34%. The 30-year was more contained near 5.20%. Gold, which had been sitting near $4,600 after the Bessent buyback rally, dropped toward $4,460 and gave back most of last week’s hard-asset bid.
Jackson Hole: more hawkish than July, still no map
Warsh recommitted to a “firm, fixed” 2% PCE target. He said short-term interest rates are the Fed’s “predominant tool.” He described financial conditions as not broadly restrictive — a step away from the July press conference, when he called them uneven and argued markets had already done some of the work. The line that traders took home: “We must be confident that underlying inflation is moving to our objective, clearly and at sufficient speed. Otherwise, we have work to do.”
He still refused forward guidance. No list of triggers before September 15–16. Bank of America called the modest equity reaction “pricing a more credible Fed.” The other read is closer to July: hawkish talk, then a hold. Moneycorp’s Eugene Epstein put it bluntly — same talking points as before the last decision, and last time the market did the work so the Fed did not have to.
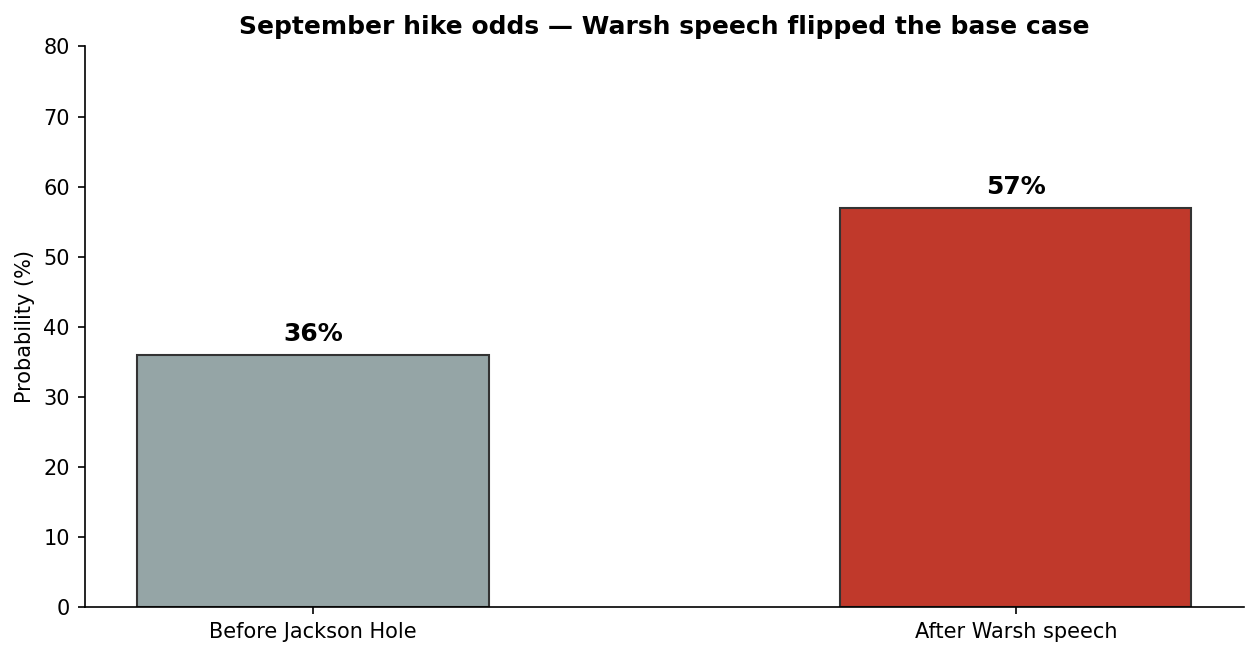
September hike probability around Warsh’s Jackson Hole speech. Source: CME FedWatch
CME FedWatch Tool. Source: https://www.cmegroup.com/markets/interest-rates/cme-fedwatch-tool.html
Bond investors: hike wagers up, conviction still low
That is the core of Bloomberg’s second piece. ABN AMRO and Brandywine are voicing skepticism that Warsh is actually poised to raise rates. Christophe Boucher at ABN AMRO said the reaction function remains unclear: if Warsh does not hike in September and inflation is still sticky, credibility concerns come back. That is why he is staying away from long-dated Treasuries. Goldman Sachs warned that a hold plus a thin explanation could whip the curve around.
The curve itself told the story. The short end sold off because a September hike is now the base case, not a tail. The long end held or even eased, because a chair who sounds serious about inflation is, in theory, better for 30-year paper than a chair who talks tough and then sits on his hands. That is a bull-flattening with an asterisk. Oil is back above $90 on fresh US–Iran fighting, Japan’s 10-year is at a 1996 high, and Friday’s NFP is the next live input. Consensus sits around +58,000 jobs, unemployment 4.1%. A hot print makes the hike easier. A weak one gives Warsh an exit — and gives the skeptics their “fool me twice” tape.
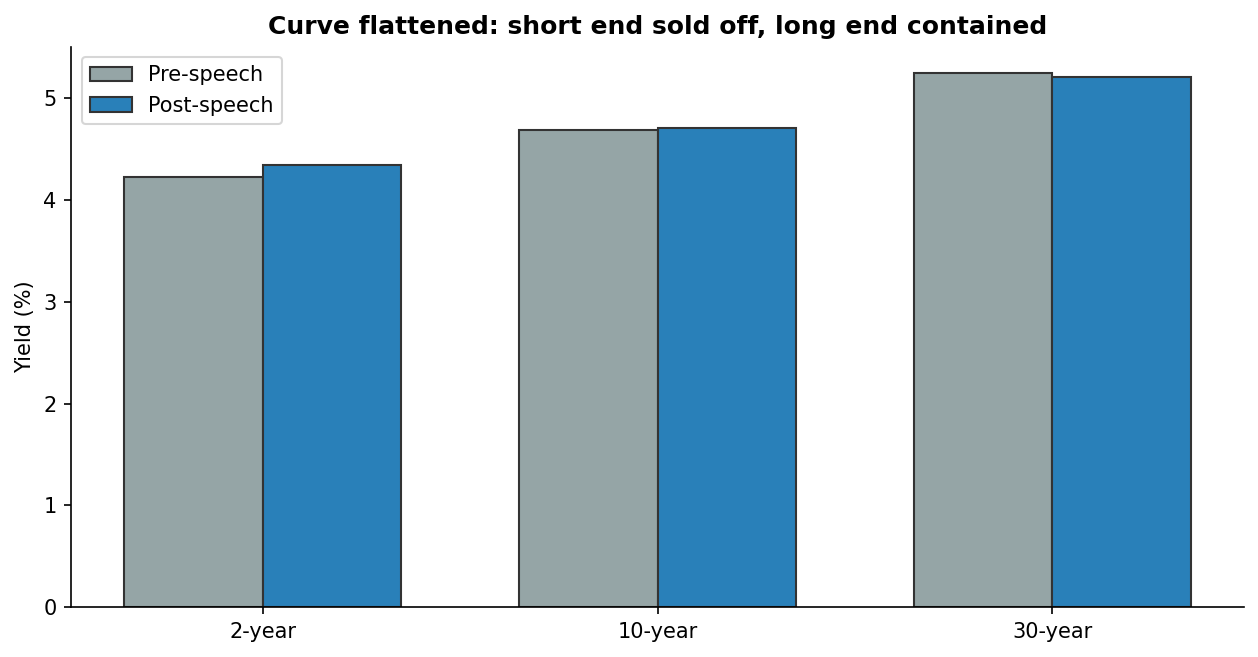
Short-end yields jumped; the long end stayed contained. Source: Bloomberg
Equities: Nvidia helped, Warsh capped it
Nvidia’s fiscal Q2 beat — revenue $96.22 billion, adjusted EPS $2.22 — was supposed to restart the AI bid. It did, for a session. Then PCE and Jackson Hole put duration back in charge. Tech led Friday’s drift. PayPal sold off on a reported takeover exit; Gap jumped after naming a new Old Navy CEO. The week was not a washout: the Nasdaq was still up on a five-day basis. It was a market that will not chase while 2-year yields reprice a hike. Asian shares slipped Monday, oil jumped about 2%, S&P futures were flat to slightly weaker. Stocks are no longer trading Bessent’s bond backstop as the main story. They are trading whether Warsh’s 100th-day speech becomes his first hike.
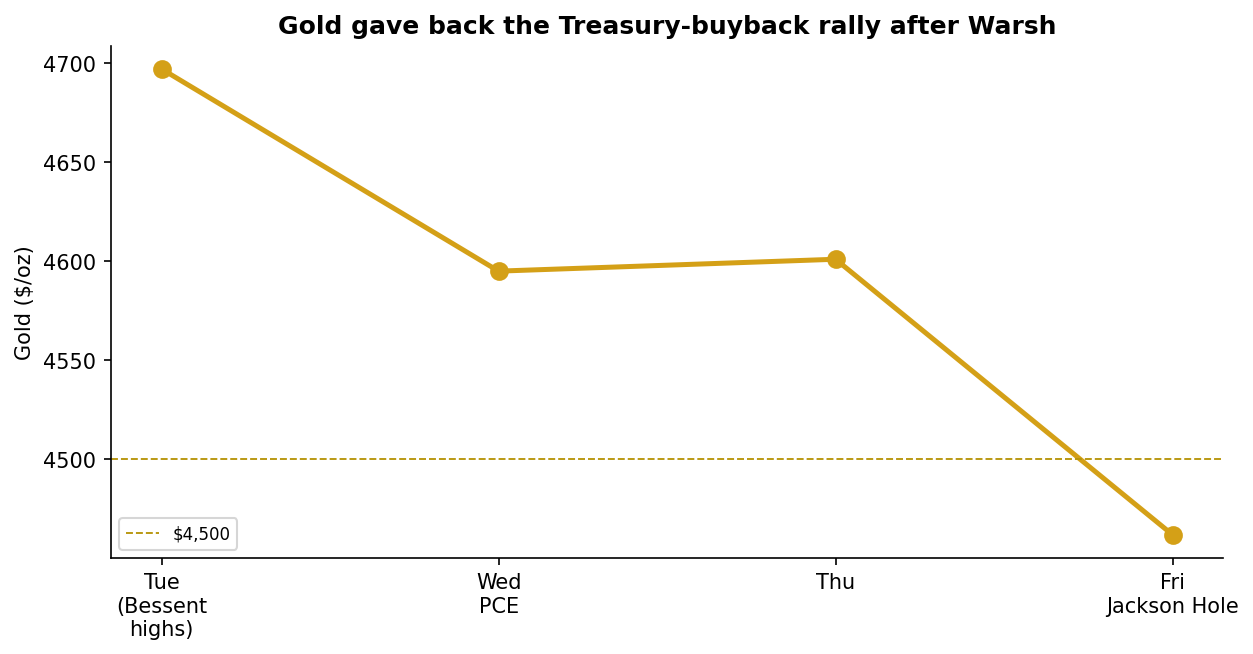
Gold gave back the Treasury-buyback rally. Source: Bloomberg
News in focus
Friday, September 4: August nonfarm payrolls — the last labor print before the FOMC.
Week of September 11: August CPI — the last inflation print before the decision.
September 9: Treasury’s enlarged long-end buybacks begin.
September 15–16: FOMC. September hike now the market’s base case at ~57%.
Now let’s shift to potential scenarios and trading ideas for the week ahead.
Gold
XAUUSD gave back the Bessent-week extension. The metal fell from the $4,600–4,700 area toward $4,460 as hike odds and the dollar rose. The constructive case needs NFP to disappoint and 2-year yields to fade — then gold can rebuild toward $4,500–4,550. Without that, $4,400–4,350 is the next support from the mid-August pause. A hot jobs print plus oil above $90 would cap any bounce. Jackson Hole ended the simple “Treasury put equals higher gold” tape.
XAUUSD, daily chart. Source: Exness.com
Nasdaq
The Nasdaq at 26,400 drifted on Friday after Nvidia’s beat failed to outrun a hawkish Fed. Support is still the 26,000–26,200 zone from the prior slump. As long as that holds into NFP, a grind toward 26,600–26,800 remains possible if the labor report is soft enough to cut hike odds back below 50%.
If payrolls come in hot, or if 2-year yields push on from 4.34%, the index can slide toward 25,500–25,800 — the same downside that was on the table when Bessent’s buybacks stopped working. Equities treated Warsh as more credible, not as a reason to sell everything. That courtesy lasts until Friday’s jobs number.
USTEC, daily chart. Source: Exness.com